How to Get Out of Debt in 2026: A Step-by-Step Guide to Choosing the Best Debt Consolidation Programs
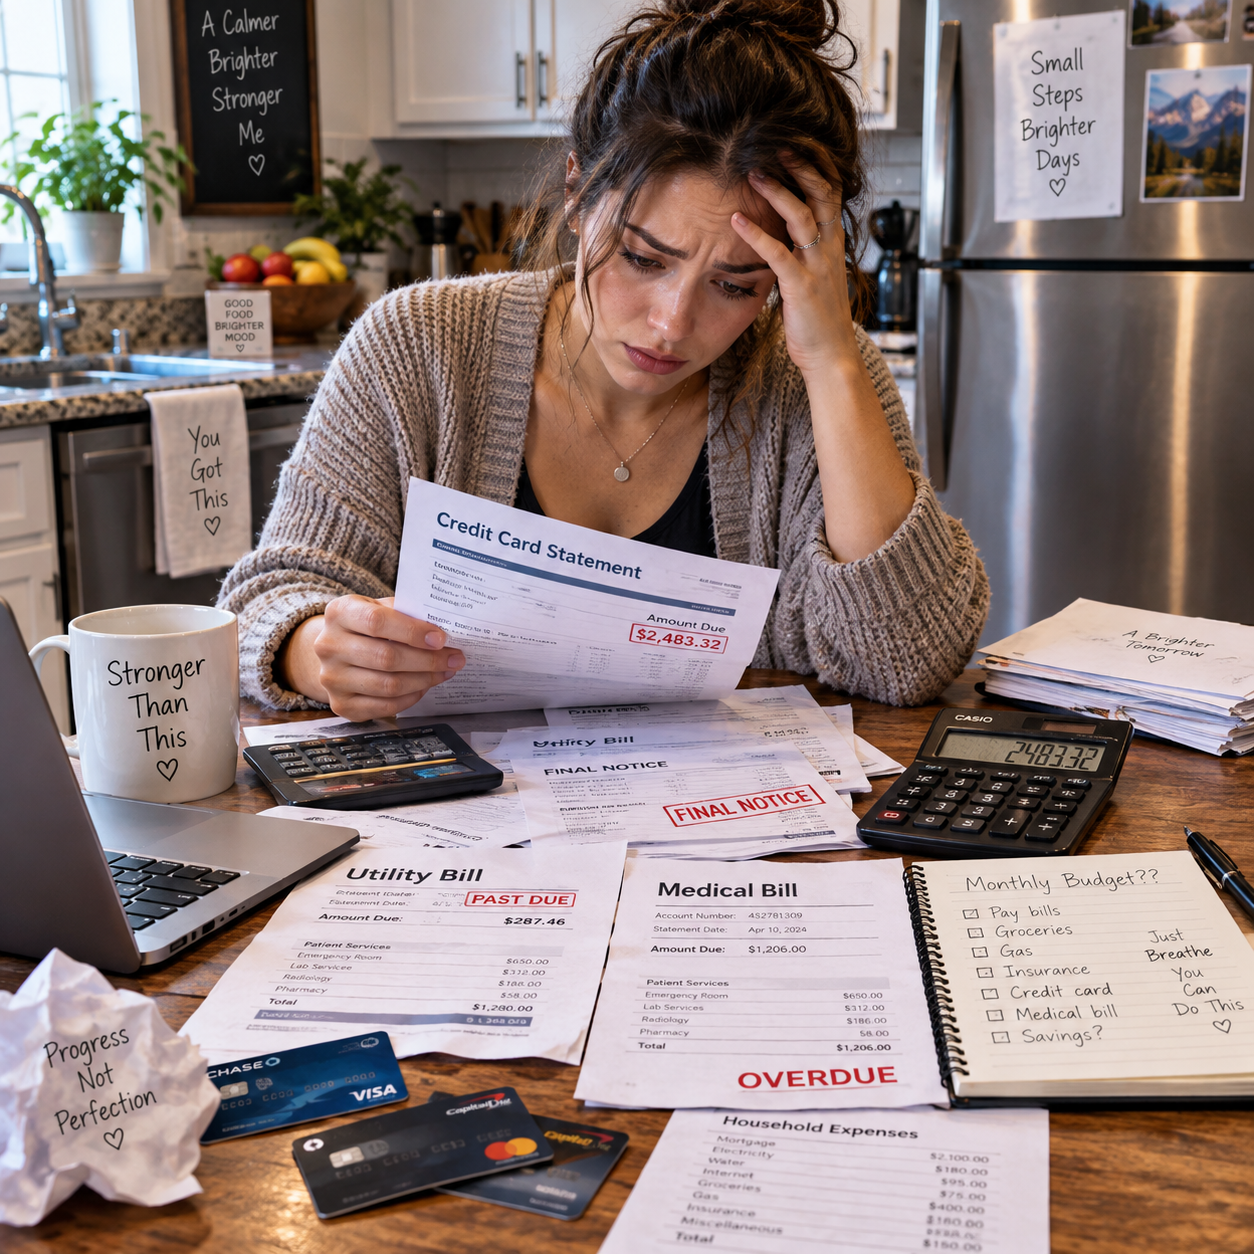
I've been there — sitting at the kitchen table at midnight with three credit card statements, a medical bill, and a personal loan notice fanned out like a bad hand of cards. If that's you right now, you're not alone. Millions of Americans are starting 2026 buried under that exact same weight, watching interest rates climb while paychecks just... sit there. It's exhausting. And honestly? It's easy to convince yourself there's no way out.
But there's real good news buried in here somewhere: debt consolidation can genuinely simplify your life by rolling multiple payments into one, often at a lower rate than what you're currently stuck paying. I put this guide together to walk you through how I'd actually evaluate your options — not the program with the flashiest ad, but the one that fits your real situation.
Understanding Debt Consolidation: What It Is and How It Works
At its core, debt consolidation means taking several debts — say, two credit cards, a medical bill, and a personal loan — and combining them into one monthly payment. Ideally, that new payment carries a lower interest rate than the average of what you were paying before. Which means more of your money goes toward the principal instead of just feeding interest charges every month.
There are a few different vehicles for doing this, and I'll say it plainly: they're not interchangeable, no matter what the ads imply. A debt consolidation loan is a fixed-term personal loan you use to pay off existing balances, leaving you with one predictable payment. A balance transfer credit card lets you move high-interest credit card debt onto a new card with a 0% or low promotional APR for a set period. And a debt management plan, typically run through a nonprofit credit counseling agency, doesn't involve new borrowing at all — instead, the agency negotiates with your creditors on your behalf, and you make one payment to them monthly.
Common Types of Debt That Can Be Consolidated
Not all debt behaves the same way once you actually try to consolidate it. I've noticed people lump everything together and then get blindsided when the numbers don't line up the way they expected. Getting these differences straight upfront helps you pick the right strategy from day one instead of course-correcting halfway through.
- Credit card debt: Usually the easiest to consolidate, since it's unsecured and often carries the highest interest rates — sometimes above 24% APR in 2026. This is where consolidation tends to deliver the biggest savings, by far.
- Medical debt: More flexible than most people realize, honestly. Hospitals and providers frequently offer interest-free payment plans, or they'll negotiate a reduced lump sum before you even need a formal loan. If it's already gone to collections, some consolidation lenders will still include it, but terms vary. A lot.
- Personal loans: These already have fixed terms, so consolidating them mainly makes sense if you can lock in a meaningfully lower rate, or you just want the simplicity of combining them with everything else.
Signs You Might Need a Debt Consolidation Program
Consolidation isn't the right move for everyone. So it helps to check whether your situation actually calls for it before you go chasing a lender. Here's what I'd watch for:
- You're only making minimum payments, and your balances barely move month to month.
- You've started using credit cards to cover groceries, gas, or utilities — not luxuries, just the essentials.
- You've missed a payment, or several, in the last six months.
- Your debt-to-income ratio has crept above 40%, meaning nearly half your income goes toward debt payments.
- You're juggling three or more creditors and losing track of due dates.
If several of these sound familiar, consolidation is worth exploring. But if your debt is truly unmanageable even with a lower rate, options like credit counseling or bankruptcy might fit better — I'll get to that comparison shortly.
Step-by-Step Guide to Choosing the Best Debt Consolidation Program
Once you've decided consolidation makes sense, the real work starts: choosing the right program. Here's how I'd approach it, step by step.
Step 1 – Assess Your Total Debt and Credit Score
Before you apply anywhere, list every single debt — balance, interest rate, minimum payment, creditor name. Add it all up. That number matters, because it determines how large a consolidation loan you'll actually need, and lenders will absolutely check your credit score before deciding what rate to offer you.
Pull your credit report for free through AnnualCreditReport.com, and check your score through your bank or a free service. A score above 670 typically opens the door to better rates. Below that? You may still qualify, but expect higher APRs — or the need for a co-signer.
Step 2 – Compare Interest Rates, Fees, and Terms
This is where a lot of people rush and end up regretting it later. Don't just eyeball the advertised APR — dig into origination fees (often 1% to 8% of the loan), prepayment penalties, and the actual repayment term. A lower monthly payment stretched over seven years can end up costing you more in total interest than a slightly higher payment over three. Counterintuitive, sure. But true.
Because rates and fee structures vary so much between lenders, I'd strongly recommend reviewing a curated comparison resource before applying anywhere. The best debt consolidation programs guide breaks down top-rated providers side by side — APR ranges, eligibility requirements, customer satisfaction scores — which makes it a lot easier to shortlist two or three options instead of just guessing and hoping for the best.
Debt Consolidation vs. Other Debt Relief Options
Consolidation isn't the only path forward, and it's worth knowing how it stacks up against the alternatives before you commit to anything.
- Debt consolidation loans: Pros — single payment, potentially lower rate, keeps accounts in good standing. Cons — requires decent credit, doesn't reduce the amount you actually owe.
- Debt settlement: Pros — can reduce total balance owed, sometimes significantly. Cons — tanks your credit score temporarily, often involves stopping payments first, and settled amounts can get taxed as income.
- Credit counseling / debt management plans: Pros — no new borrowing, professional negotiation, structured payoff timeline. Cons — may require closing credit accounts, takes 3-5 years typically.
- Bankruptcy (Chapter 7 or 13): Pros — legal protection, can discharge unsecured debt including some medical bills. Cons — major long-term credit impact, court involvement, not ideal if you've got assets to protect.
For someone drowning mostly in medical debt, I'd lean toward a debt management plan or direct negotiation with providers rather than a loan — medical debt is frequently negotiable outside formal consolidation anyway. For heavy credit card debt with steady income, though, a consolidation loan or balance transfer usually makes the most sense.
Common Mistakes to Avoid When Consolidating Debt
I've watched people do everything right up until the final step, then quietly undo their own progress. Here's what to watch for:
- Closing old credit card accounts immediately after paying them off — this can shrink your available credit and hurt your credit utilization ratio.
- Racking up new balances on those now-empty cards, which defeats the entire point of consolidating in the first place.
- Skipping the fine print on fees — origination fees, late payment penalties, and balance transfer fees can quietly eat into whatever you're saving.
- Not checking a lender's reputation through the Better Business Bureau or Consumer Financial Protection Bureau complaint database before signing anything.
Tips for Staying Debt-Free After Consolidation
Getting the loan or plan set up is only half the battle — staying debt-free is the real win, and it's the part people tend to underestimate. Start by building even a small emergency fund, $500 to $1,000, so an unexpected car repair doesn't send you right back to a credit card. Create a realistic monthly budget that accounts for your new consolidated payment, and automate it so you never miss a due date.
Over the following 12 to 24 months, track your credit score monthly. You should see steady improvement as your credit utilization drops and your payment history builds a genuinely positive track record. Slowly. But it happens.
Frequently Asked Questions (FAQ)
Does debt consolidation hurt my credit score? There's usually a small, temporary dip from the credit check and new account, but most people see their score improve within a few months as they make consistent payments and reduce credit utilization.
Can medical debt be included in a consolidation loan? Yes — most personal loan consolidation programs will include medical debt alongside credit card and personal loan balances, though it helps to negotiate directly with providers first, since medical bills are often reducible on their own.
How long does debt consolidation take to improve my finances? Many people notice less monthly stress within the first payment cycle, but meaningful credit score improvement and debt reduction typically take 12 to 24 months of consistent payments.
Is debt consolidation the same as debt settlement? No. Consolidation combines your debts into one payment without reducing what you owe, while settlement negotiates to pay less than the full balance — often at the cost of your credit score.
Getting out of debt in 2026 isn't about finding some magic fix. It's about taking a clear-eyed look at what you actually owe, understanding your real options, and choosing the consolidation program that fits your income and your goals — not someone else's. Whether you're dealing with credit card balances, medical bills, or a personal loan that's spiraled out of control, a methodical, step-by-step approach beats panic every single time. Take the time to compare rates and terms carefully before signing anything, and you'll be in a far stronger position a year from now than you are today.